ACH File Slippage at a Glance
When I was building the payroll chronometry algorithms for our 48-country banking calendar API, the ACH file slip was by far the most frequent issue corporate controllers asked me to diagnose. Few things trigger more immediate panic across a company than an employee calling payroll at 8:00 AM on payday because their checking account is empty. In nearly every holiday-related payroll delay I have investigated, the issue was not a lost wire or a banking computer crash. It was a simple misunderstanding of how the ACH operator parses a single six-digit date field inside the batch header.
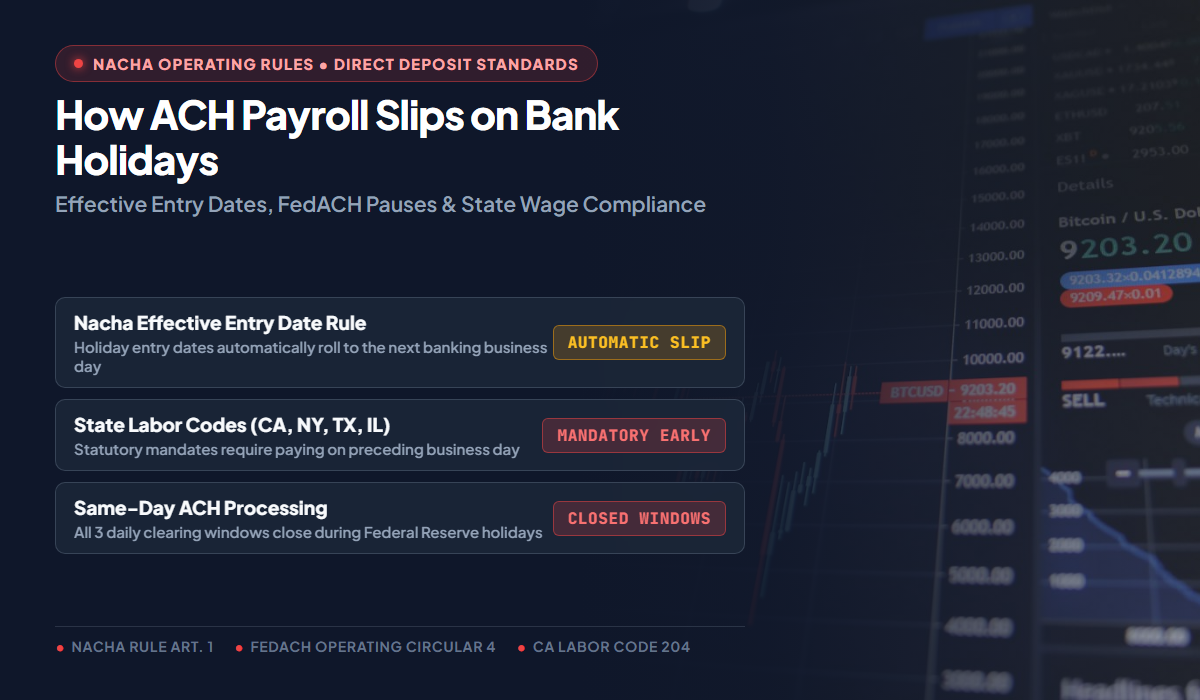
When a payroll administrator enters a federal holiday as the intended payday, the clearing network does not reject the file or call to warn you. Instead, the clearing engine quietly pushes the entire batch forward to the next open banking business day. For FedACH items, this deferral is governed by Federal Reserve Operating Circular No. 4 Section 3.2. Below is my verified operational breakdown, drawn directly from our API tests, Nacha Operating Rules, and Federal Reserve operating circulars. To verify upcoming central bank closures across all rails, you can cross-reference our United States Public Holidays Calendar.
Pos 64-69 (Field 9):  [261012] -> Optional Company Descriptive Date (Informational, e.g. Oct 12, 2026)
Pos 70-75 (Field 10): [261013] -> Effective Entry Date (YYMMDD: Intended banking settlement day)
*Rule: If Pos 70-75 = 261012 (Columbus Day), FedACH defers settlement to 261013 under OC 4 Section 3.2
The Anatomy of an ACH Slip: ODFI, FedACH & RDFI
When I trace an ACH direct deposit through the banking pipeline, I break the journey into three distinct institutional checkpoints. Understanding where the file sits at each hour is the only way to pinpoint why funds did not post on time:
- The Originator & ODFI: The employer (the Originator) compiles employee wage records into a standard 94-character fixed-width NACHA data file and transmits it to their commercial bank, the Originating Depository Financial Institution (ODFI). In my testing with commercial cash management portals, I found that each ODFI sets its own rigid submission deadline, often hours ahead of operator windows. If you miss your bank's internal cutoff by five minutes, your batch sits idle until the next business cycle.
- The ACH Operator (FedACH or EPN): Once validated, the ODFI transmits the batch to an authorized ACH Operator. In the United States, there are two licensed operators: FedACH (operated by the 12 Federal Reserve Banks) and The Clearing House EPN (Electronic Payments Network). The operator acts as the central clearinghouse, sorting millions of credits and debits and calculating the net settlement balances between participating financial institutions.
- The RDFI: The Receiving Depository Financial Institution is the commercial bank, credit union, or digital bank where the employee maintains their checking or savings account. The RDFI receives the sorted batch from the operator, validates the account details, and posts the credit to the employee's ledger.
A critical operational distinction that I always emphasize when auditing payroll systems is the difference between file processing and funds settlement. Many payroll managers assume that the entire electronic banking network goes completely dark on a federal holiday. In my review of Federal Reserve operating circulars, that is not what happens. Under Title 5 of the United States Code (5 U.S.C. 6103) and Federal Reserve Operating Circular No. 4, the Federal Reserve Banks observe eleven statutory holidays, which means interbank settlement accounts are closed and zero net money moves across Reserve Bank ledgers.
However, electronic file processing by the ACH Operator does not necessarily shut down for the entire holiday. For example, when I inspected the FedACH holiday operating schedule for Thanksgiving 2026, file processing closes on Wednesday, November 25 at 11:30 PM ET and reopens on Thursday, November 26 at 5:30 PM ET for Friday's settlement. The operator's intake servers can accept and stage files during that Thursday evening window, but no interbank funds settle on the holiday itself.
Nacha Header Rules: The Effective Entry Date Trap
When I wrote our file parser for NACHA format Record Type 5 (the Company/Batch Header Record), I noticed that nearly every software bug that caused delayed employee pay stemmed from confusing two specific date fields:
- Positions 64-69 (Field 9): Company Descriptive Date. This is an optional six-character alphanumeric field. In my audits, I have seen employers put descriptive text like "PAYDAY", "OCT 12", or "261012" here. It is displayed on the employee's bank statement for identification purposes, but the ACH Operator's settlement engine ignores it entirely.
- Positions 70-75 (Field 10): Effective Entry Date. This is the operational engine of the batch header, formatted strictly as YYMMDD. The Effective Entry Date represents the Originator's intended banking settlement date between financial institutions. It is not a legal guarantee of the exact minute an employee sees cash in their mobile app, but it tells the ACH Operator when interbank value should transfer.
When an Originator enters a date that falls on a weekend or Federal Reserve holiday into Field 10, how does the clearing engine react? For FedACH and Reserve Bank items, Federal Reserve Operating Circular No. 4 Section 3.2 establishes the governing settlement rule:
Let us examine a concrete case from my chronometry simulations: Columbus Day 2026. Suppose an employer's regular semi-monthly payday falls on Monday, October 12, 2026 (Columbus Day / Indigenous Peoples' Day). If the payroll clerk enters October 12, 2026 (coded as 261012) into Field 10, the Reserve Bank cannot settle on that day because its settlement windows are closed. Under Operating Circular No. 4 Section 3.2, FedACH automatically assigns the next banking business day, Tuesday, October 13, 2026, as the settlement date. FedACH does not reject the file; it simply defers settlement. If that employer wanted their staff to have funds in hand before the long holiday weekend, they had to set Field 10 to Friday, October 9, 2026 (261009) and transmit the file ahead of their ODFI's Friday cutoff.
You can see how this banking operational pause contrasts with equity trading in our companion analysis of why stock markets trade on Columbus Day while Fedwire halts.
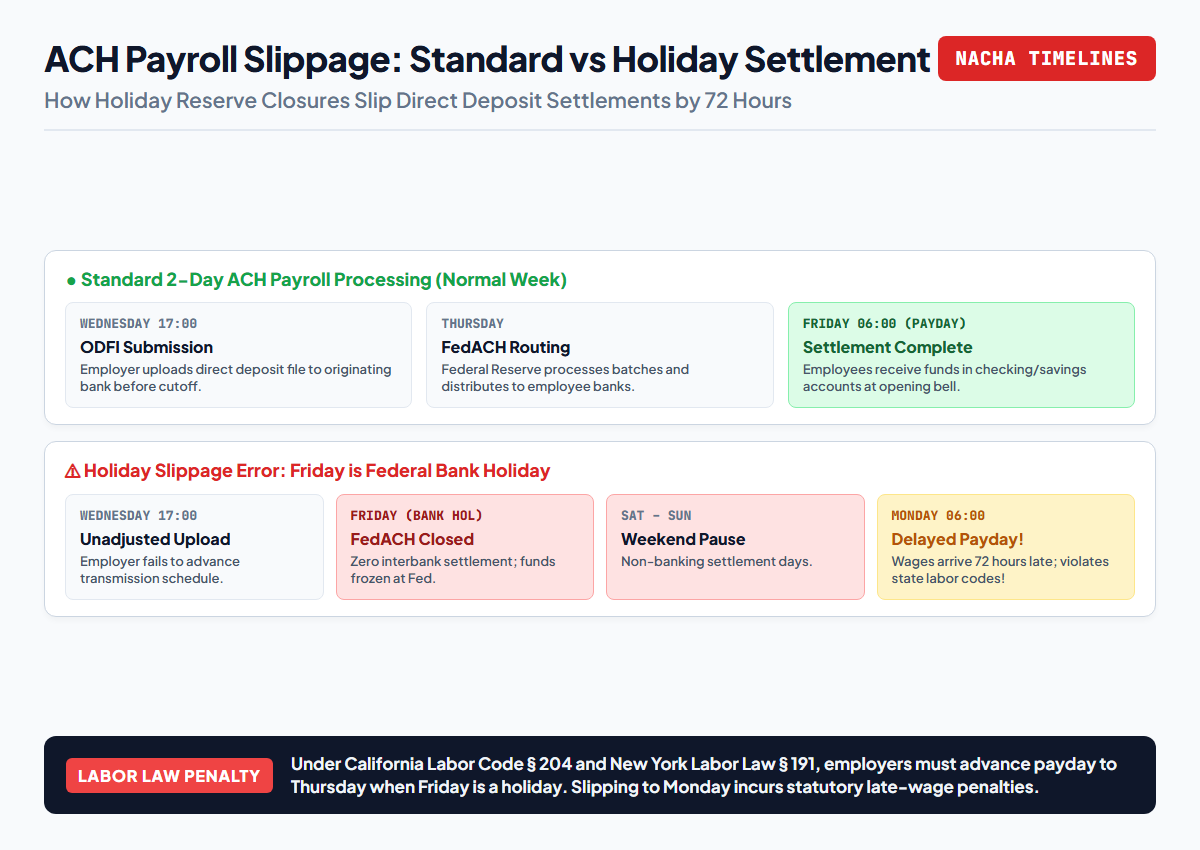
Visual Guide: Standard vs. Holiday-Slipped Clearing Windows
To help controllers and payroll software teams visualize this sequence, I mapped out the clearing lifecycle below. It contrasts a normal two-day cycle against a holiday-delayed cycle:
To verify business day counts and prevent weekend slippage in your payroll schedules, you can use our interactive Working Days Calculator.
Same-Day ACH Limitations During Federal Reserve Pauses
Whenever an ACH file slips, the first emergency fix payroll managers ask me about is: "Can we just push an emergency Same-Day ACH batch this morning to bail ourselves out?" My answer is always a hard reality check: No, you cannot.
Under Nacha Operating Rules, Same-Day ACH allows originating institutions to clear payments up to $1,000,000 per transaction across three daily processing windows. It is a powerful tool for emergency corrections during the normal business week. But here is the critical operational constraint: Same-Day ACH does not settle on Federal Reserve holidays or weekends.
Same-Day ACH relies directly on the Federal Reserve's National Settlement Service (NSS) to move actual reserves between the ODFI and RDFI. When the Federal Reserve Banks observe a statutory holiday, the NSS window is closed. If your HR department discovers on Monday morning (Columbus Day, Memorial Day, or Labor Day) that employees were not paid, submitting a Same-Day ACH file on Monday morning does nothing. The operator will not clear the transactions until Tuesday.
In my review of FedACH operating schedules, I also caution teams about treating operator transmission deadlines as employer submission cutoffs. For instance, FedACH publishes an operator-to-operator deadline of 10:30 AM ET targeting a 1:00 PM ET settlement. That deadline is when your bank must transmit to the Federal Reserve, not when you can upload to your bank. Your bank sets an earlier internal cutoff to run fraud checks and format the files. Furthermore, even after FedACH settles with the receiving bank, each RDFI controls the exact moment those funds post to the employee's account ledger.
State Labor Laws: Mandatory Early vs. Permitted Late Paydays
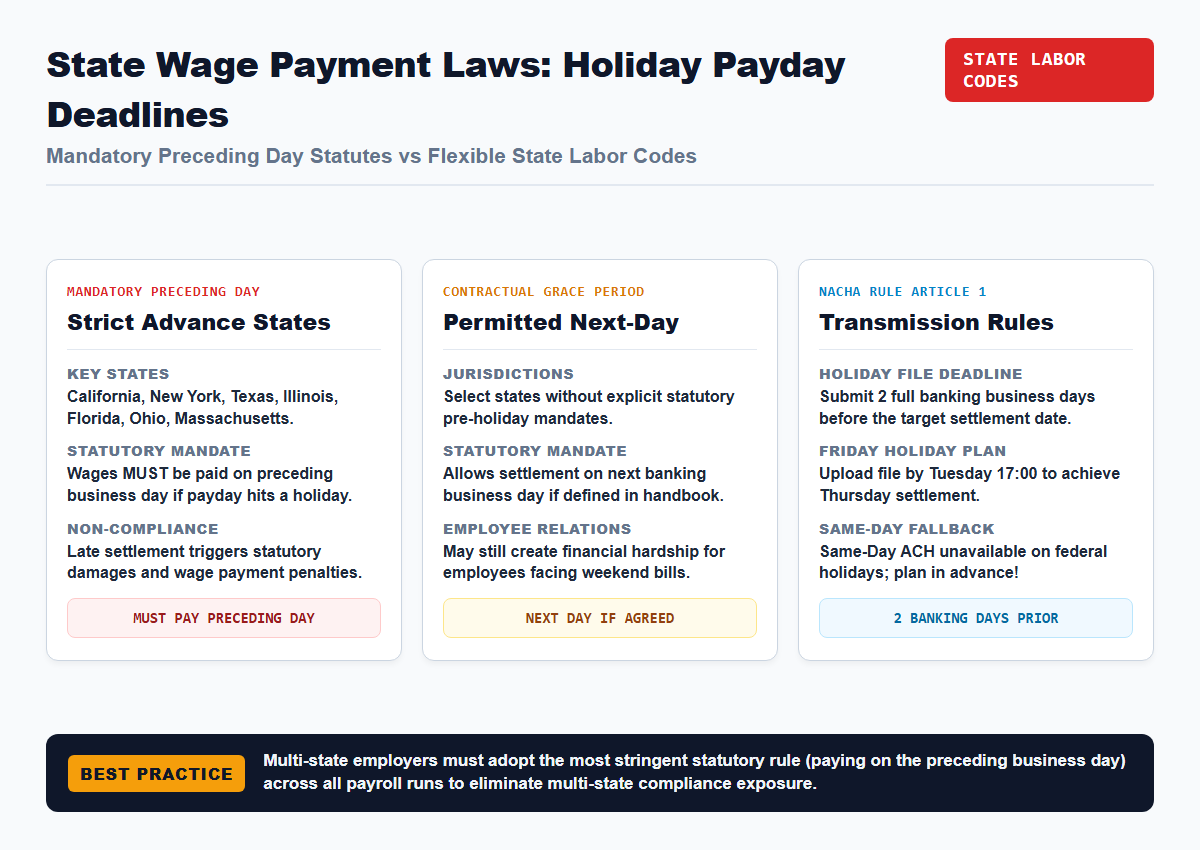
When I researched state wage payment statutes to build our chronometry compliance rule set, I wanted to verify whether federal or state law legally compels an employer to pay on the preceding business day when a payday coincides with a bank holiday. Here is what my audit of the labor codes revealed:
First, the federal standard: under the Fair Labor Standards Act (FLSA, 29 U.S.C. 201 et seq.), covered non-exempt wages are required to be paid on the regular payday designated by the employer for that pay period. However, the FLSA establishes zero statutory holiday calendar rules. The federal statute does not mandate what happens when a payday lands on a banking holiday. That issue is governed entirely by state wage payment laws, employment contracts, and established employer policies.
Second, when I audited state-level codes, I discovered that the common belief that all states legally mandate early payment is false. Below is the factual statutory reality across key states:
| State Jurisdiction | Statutory & Administrative Holiday Payday Rules | Governing Legal Statute / Authority | Employer Compliance Note |
|---|---|---|---|
| California | If an employer is closed for business on a holiday payday, payment may be made on the next business day (DLSE FAQ) | Cal. Lab. Code Section 204; Cal. Civ. Code Section 11 | Permitted timing when closed; statutory penalties under Section 210 require a qualifying failure to pay |
| New York | Sets pay frequency by worker category (e.g. manual workers weekly); does not expressly require preceding-day payment for holidays | NY Labor Law Section 191; NY DOL Guidance | Employers must comply with statutory pay frequency and established payroll policy |
| Texas | When an employer is normally closed on a regular payday, payment is due on the next regular business day (TWC guidance) | Tex. Labor Code Sections 61.011-61.012 (Section 61.014 covers final wages) | TWC guidance provides safe harbor to pay on next business day when normally closed |
| Florida | No state statute regulating paydays or holiday timing for private employers; Fla. Stat. Section 110.113 governs state government employees | U.S. DOL State Payday Table; Fla. Stat. Section 110.113 | Private employers follow FLSA baseline, employment agreement, or designated policy |
| Illinois | Wages must be paid within 13 days of pay period end for semi-monthly/biweekly pay (820 ILCS 115/4); no automatic early-holiday mandate | 820 ILCS 115/4 (Wage Payment and Collection Act) | 13-day lag is measured from the pay period close, not a universal maximum between paydays |
| Pennsylvania | Requires designated regular paydays in advance; does not mandate payment on the preceding day for holidays | 43 P.S. Section 260.3 (Wage Payment and Collection Law) | Timing depends on employment agreement, written policy, and established practice |
In my opinion and based on my consultations with payroll directors, an employer may choose to adopt an internal policy of paying on the preceding business day when a regular payday coincides with a bank holiday. This is often the best operational practice to maintain employee trust and prevent personal overdrafts. However, doing so is a company policy choice, subject to applicable state laws, employment contracts, and ODFI cutoffs, rather than a universal federal mandate.
The Payroll Administrator Playbook: Submission Deadlines
Based on my audits of banking circulars and corporate payroll workflows, here is the exact operational playbook I recommend to payroll administrators and controllers to prevent holiday payment slippage:
Never rely on early direct deposit fintechs (such as Chime or SoFi) as your compliance safety net. Early availability happens solely because the receiving institution chooses to advance its own ledger balance upon receiving the uncredited ACH memo file. If an employer submits a batch late or an ODFI cutoff is missed, there is no memo file, and no early pay will occur. Always set the Effective Entry Date to the banking day preceding the holiday and confirm your ODFI's exact transmission deadline.
- Confirm Origination Cutoffs with Your Specific ODFI or Processor: I cannot stress this enough: there is no universal 48-hour buffer or nationwide Wednesday cutoff. Origination schedules and transmission deadlines are established independently by each financial institution and payroll software vendor. I always advise controllers to obtain their bank's written cutoff schedule and work backward from their target settlement date.
- Build Holiday Lead Time Backward from Settlement: When a Federal Reserve banking holiday intervenes before or on a scheduled payday, employers must submit files according to their provider's holiday schedule to ensure settlement occurs on or before the intended date. If you want settlement on Friday before a Monday holiday, your batch must be originated ahead of your ODFI's cutoff for Friday settlement.
- Understand Prenotifications vs. Early Direct Deposit: In our API tests, a prenotification (prenote) is strictly a zero-dollar validation entry used to verify an employee's routing and account number before live payroll begins. It is not advance notice of an upcoming paycheck. Early direct deposit offered by certain financial institutions is an optional, uncredited balance advance granted when the bank receives the actual live payroll credit file ahead of the settlement date. Early posting is never guaranteed and depends entirely on when the file is originated and the receiving bank's credit risk policies.
For corporate teams coordinating cross-border payroll between US and European subsidiaries, you can compare these constraints with our technical guide to European TARGET2 non-clearing holiday dates.
To plan corporate holiday schedules and company bridge days for the upcoming year, explore our 2026 PTO Maximizer Tool.
Sources & Statutory Methodology
ACH operational regulations, settlement mechanisms, and wage compliance standards are derived from the 2026 Nacha Operating Rules & Guidelines, Federal Reserve Operating Circular No. 4 (Automated Clearing House Items, Section 3.2), Title 5 of the United States Code (5 U.S.C. 6103), the Fair Labor Standards Act (29 U.S.C. 201 et seq.), California Labor Code Section 204 and DLSE guidance, New York Labor Law Section 191, Texas Labor Code Chapter 61 and TWC guidance, Illinois Wage Payment and Collection Act (820 ILCS 115/4), and Pennsylvania Wage Payment and Collection Law (43 P.S. Section 260.3).
Written by Sahin Choudhury
Founder and lead researcher at HolidayExplore. Researching statutory calendars, central banking clearing schedules, and workplace award regulations.